
6 ODE Theory and Properties
A system of Ordinary Differential Equations (ODEs) consists of one or more equations that describe the relationship between one or more unknown functions and their derivatives (see [1],[2])
6.1 Notation Conventions
Throughout this part, t denotes the independent variable and y the unknown. The theory is stated for \bm{y}(t) with values in \mathbb R^d, but the numerical chapters that follow are written in the scalar case so as not to burden the formulas: every scheme and every estimate carries over to systems by replacing y with \bm{y}, f with \bm{f}, and the absolute value with a norm. Quantities that are vectors or matrices even in the scalar case — such as the coefficients \bm{A}, \bm{b}, \bm{c} of a Butcher tableau — stay bold.
The symbols used consistently are:
| symbol | meaning |
|---|---|
| t_k, h | mesh points and step size, t_{k+1}=t_k+h |
| y(t_k) | exact solution at t_k |
| y_k, \bm{z}_k | numerical approximation of y(t_k) (scalar, vector) |
| e_k=y(t_k)-y_k | global error |
| \tau_k | local truncation error / local defect |
| \Psi(t,y;h) | increment function of a one-step method |
| L | Lipschitz constant of f with respect to y |
| \bm{J}_{\bm{f}} | Jacobian \partial\bm{f}/\partial\bm{y} |
| p | order of the method |
| q=h\lambda, R(q), \mathcal S | scaled eigenvalue, stability function, stability region |
6.2 Examples of ODEs
Scalar ODEs
In this section, we present several examples of first-order ordinary differential equations, highlighting their structure and how they are defined in terms of a function f(y,x), with the state variable first and the independent variable second.
Example 6.1 Nonlinear first-order ODE.
\left\{ \begin{aligned} y' &= y^2 + x \\ y(0) &= 1 \end{aligned} \right. \implies \color{magenta} \begin{aligned} y'(x) &= y(x)^2 + x = f(y(x),x), \\ f(y,x) &= y^2 + x \end{aligned}
Example 6.2 ODE with mixed linear and nonlinear terms.
\left\{ \begin{aligned} y' &= xy + y^2 \\ y(0) &= 2 \end{aligned} \right. \implies \color{magenta} \begin{aligned} y'(x) &= xy(x) + y(x)^2 = f(y(x),x), \\ f(y,x) &= xy + y^2 \end{aligned}
Example 6.3 ODE with a trigonometric nonlinearity.
\left\{ \begin{aligned} z' &= x^2 + \sin z \\ z(-1) &= 0 \end{aligned} \right. \implies \color{magenta} \begin{aligned} z'(x) &= x^2 + \sin z(x) = f(z(x),x), \\ f(z,x) &= x^2 + \sin z \end{aligned}
Example 6.4 Logistic growth model.
\left\{ \begin{aligned} p' &= r p \left(1 - \frac{p}{K} \right) \\ p(0) &= p_0 \end{aligned} \right. \implies \color{magenta} p'(t) = r p(t) \left(1 - \frac{p(t)}{K} \right)
- Models population growth, where p represents the population size.
- Parameters:
- r = growth rate.
- K = carrying capacity of the environment.
- Applications: Used in ecology and epidemiology.
Example 6.5 Newton’s law of cooling.
\left\{ \begin{aligned} T' &= -k(T - T_{\text{env}}) \\ T(0) &= T_0 \end{aligned} \right. \implies \color{magenta} T'(t) = -k (T - T_{\text{env}})
- Describes how an object cools down over time.
- Parameters:
- k = heat transfer coefficient.
- T_{\text{env}} = ambient temperature.
Systems of ODEs
Example 6.6 A simple two-variable system.
The following system describes the evolution of two state variables x(t) and y(t):
\left\{ \begin{aligned} &\left. \begin{aligned} x' & = x+y \\ y' & = \mathrm{e}^x-y \end{aligned} \right\} \quad \color{magenta} \text{ODE equations} \\ &\left. \begin{aligned} x(0) & = 1 \\ y(0) & = 1 \end{aligned} \right\} \quad \color{magenta} \text{Initial conditions} \end{aligned} \right.
- The first equation describes the rate of change of x, which depends on both x and y.
- The second equation models the evolution of y, which depends on an exponential function of x and y itself.
- The system starts from the initial state (x(0), y(0)) = (1,1).
Example 6.7 A three-variable coupled system.
This example involves three interdependent variables x, w, and z, with an explicit time dependence in the third equation.
\left\{ \begin{aligned} &\left. \begin{aligned} z' & = x+z \\ w' & = z \\ x' & = wz+t \end{aligned} \right\} \quad \color{magenta} \text{ODE equations} \\ &\left. \begin{aligned} x(0) & = 1 \\ w(0) & = 1 \\ z(0) & = 1 \\ \end{aligned} \right\} \quad \color{magenta} \text{Initial conditions} \end{aligned} \right.
6.3 Vector Form of ODEs
A system of first-order ODEs can be expressed in vector notation, which provides a more compact and structured representation of the problem. This notation is particularly useful in numerical methods and theoretical analysis.
System of ODEs in Scalar Form
Consider a system of n first-order ordinary differential equations:
y_1(t), y_2(t), \dots, y_n(t),\qquad \color{magenta} \text{functions of } t
The system is given by:
\left\{ \begin{aligned} &\left. \begin{aligned} y_1' &= f_1(t, y_1, y_2, \dots, y_n) \\ y_2' &= f_2(t, y_1, y_2, \dots, y_n) \\ &\vdots \\ y_n' &= f_n(t, y_1, y_2, \dots, y_n) \\ \end{aligned} \right\} \quad \color{magenta} \text{ODE system} \\ &\left. \begin{aligned} y_1(0) &= y_1^0, \\ y_2(0) &= y_2^0, \\ &\vdots\\ y_n(0) &= y_n^0, \end{aligned} \right\} \quad \color{magenta} \text{Initial conditions} \end{aligned} \right.
Compact Vector Form
To write this system in vector notation, define:
The state vector:
\bm{y}(t) = \begin{pmatrix} y_1(t) \\ y_2(t) \\ \vdots \\ y_n(t) \end{pmatrix}
The function that describes the system dynamics:
\bm{f}(\bm{y},t) = \begin{pmatrix} f_1(y_1, y_2, \dots, y_n,t) \\ f_2(y_1, y_2, \dots, y_n,t) \\ \vdots \\ f_n(y_1, y_2, \dots, y_n,t) \end{pmatrix}
The initial condition vector:
\bm{y}_0 = \begin{pmatrix} y_1^0 \\ y_2^0 \\ \vdots \\ y_n^0 \end{pmatrix}
Thus, the system can be rewritten in vector form as:
\left\{ \begin{aligned} \bm{y}' &= \bm{f}(\bm{y},t), \qquad\implies\quad \color{magenta} \bm{y}'(t)=\bm{f}(\bm{y}(t),t)\\ \bm{y}(0) &= \bm{y}_0 \end{aligned} \right.
This notation simplifies analysis and computation, particularly in numerical solvers.
Matrix Form of a Linear System
When the system is linear, meaning the functions f_i(t,\bm{y}) depend linearly on \bm{y}, the system can be written as:
\bm{y}' = \bm{A}(t) \bm{y} + \bm{b}(t)
where:
- \bm{A}(t) is an n \times n matrix of coefficients.
- \bm{b}(t) is a vector of external inputs (or forcing terms).
- If \bm{b}(t) = \bm{0}, the system is homogeneous; otherwise, it is inhomogeneous.
A simple example of a homogeneous linear system is
\bm{y}'=\bm{A}\bm{y}, \qquad \bm{y}= \begin{pmatrix} y_1\\y_2 \end{pmatrix}, \qquad \bm{A}= \begin{pmatrix} a_{11}&a_{12}\\ a_{21}&a_{22} \end{pmatrix}.
This formulation allows for powerful solution techniques, such as matrix exponentiation and eigenvalue analysis.
Constant-coefficient linear systems
For the autonomous homogeneous system
\bm{y}'(t)=\bm{A}\bm{y}(t), \qquad \bm{y}(t_0)=\bm{y}_0,
the exact solution is
\boxed{\bm{y}(t)=e^{(t-t_0)\bm{A}}\bm{y}_0},
where the matrix exponential is defined by the absolutely convergent series
e^{t\bm{A}}=\bm{I}+t\bm{A}+\frac{t^2\bm{A}^2}{2!}+\frac{t^3\bm{A}^3}{3!}+\cdots.
Indeed,
\frac{\mathrm d}{\mathrm dt}e^{(t-t_0)\bm{A}} =\bm{A}e^{(t-t_0)\bm{A}}, \qquad e^{0\bm{A}}=\bm{I}.
If \bm{A}=\bm{V}\bm{\Lambda}\bm{V}^{-1} is diagonalizable, then
e^{t\bm{A}}=\bm{V}e^{t\bm{\Lambda}}\bm{V}^{-1},
so each eigenvalue \lambda_i produces a modal factor e^{\lambda_i t}. In particular, modes with \operatorname{Re}\lambda_i<0 decay and modes with \operatorname{Re}\lambda_i>0 grow. This observation is the bridge between the continuous dynamics of a linear system and the absolute-stability analysis of numerical methods.
For the inhomogeneous constant-coefficient system
\bm{y}'=\bm{A}\bm{y}+\bm{b}(t),
the variation-of-constants formula is
$$ .
$$
Equilibria and linearization of autonomous systems
Consider an autonomous system
\bm{y}'=\bm{f}(\bm{y}), \qquad \bm{y}\in\mathbb R^d.
A point \bm{y}^\star is an equilibrium (or stationary point) if
\bm{f}(\bm{y}^\star)=\bm{0}.
The constant function \bm{y}(t)\equiv\bm{y}^\star is then an exact solution. To understand the behavior of nearby trajectories, write
\bm{y}=\bm{y}^\star+\bm{u}.
If \bm{f}\in C^1, Taylor expansion gives
\bm{f}(\bm{y}^\star+\bm{u}) = \bm{f}(\bm{y}^\star) + \bm{J}_{\bm{f}}(\bm{y}^\star)\bm{u} + \bm{r}(\bm{u}), \qquad \frac{\|\bm{r}(\bm{u})\|}{\|\bm{u}\|}\to0.
Since \bm{f}(\bm{y}^\star)=\bm{0},
\boxed{ \bm{u}' = \bm{J}_{\bm{f}}(\bm{y}^\star)\bm{u} + \bm{r}(\bm{u}) }
and the associated linearized system is
\boxed{ \bm{u}'=\bm{J}_{\bm{f}}(\bm{y}^\star)\bm{u}. }
The eigenvalues of the Jacobian matrix \bm{J}_{\bm{f}}(\bm{y}^\star) determine the local behavior whenever the equilibrium is hyperbolic, i.e. no eigenvalue has zero real part.
- If every eigenvalue satisfies \operatorname{Re}\lambda_i<0, the equilibrium is locally asymptotically stable.
- If at least one eigenvalue has \operatorname{Re}\lambda_i>0, the equilibrium is unstable.
- If eigenvalues lie on the imaginary axis, linearization alone is generally inconclusive; nonlinear terms may determine stability.
For a hyperbolic equilibrium, the Hartman–Grobman theorem gives a much stronger qualitative statement: sufficiently close to the equilibrium, the nonlinear flow is topologically equivalent to its linearization. For numerical analysis, the same eigenvalues also reveal the time scales of the local dynamics and are therefore closely related to stiffness.
Example: planar saddle and stable node
For
\bm{y}'=\bm{A}\bm{y}, \qquad \bm{A}= \begin{pmatrix} -1&0\\ 0&-10 \end{pmatrix},
both eigenvalues are negative, so the origin is asymptotically stable. The two decay time scales, 1 and 1/10, are already separated. Replacing the second eigenvalue by +10 makes the origin a saddle and therefore unstable.
6.4 General ODEs and Basic Definitions
Before exploring numerical solution methods, it is useful to briefly review some key definitions and properties of ordinary differential equations (ODEs) and initial value problems (IVPs).
Definition 6.1 (Ordinary Differential Equation) An ordinary differential equation (ODE) is an equation involving a function z(t), defined on an interval I \subset \mathbb{R}, with values in either real or complex numbers, or in the vector spaces \mathbb{R}^d or \mathbb{C}^d. The general form of an ODE is:
\bm{f}\left(\bm{z}(t), \bm{z}'(t), \bm{z}''(t), \dots, \bm{z}^{(n)}(t),t\right) = 0
Here, \bm{f} is a function that depends on time t, the unknown function \bm{z}(t), and its derivatives up to order n. The order of the differential equation is determined by the highest derivative \bm{z}^{(n)}(t) that appears.
If \bm{z}(t) takes values in a space of dimension d > 1, the equation is called a system of differential equations.
This implicit form is very general. In many IVPs of interest, the highest derivative can be isolated, leading to an explicit ODE:
Definition 6.2 (Explicit ODE) An explicit first-order differential equation has the form: \bm{z}'(t) = \bm{f}\left(\bm{z}(t),t\right) \quad \text{or briefly:} \quad \bm{z}' = \bm{f}(\bm{z},t) \tag{6.1}
For a higher-order equation (order n), the equation is called explicit if it can be written as:
\bm{z}^{(n)}(t) = \bm{f}\left(\bm{z}(t), \bm{z}'(t), \bm{z}''(t), \dots, \bm{z}^{(n-1)}(t),t\right)
Definition 6.3 (Autonomous ODE) A differential equation of the form Equation 6.1 is called autonomous if the right-hand side f does not explicitly depend on t, meaning:
\bm{z}'(t) = \bm{f}\left(\bm{z}(t)\right)
Numerical methods are often designed specifically for first-order ODEs. Therefore, higher-order ODEs must be transformed into an equivalent system of first-order equations before applying these methods.
Lemma 6.1 (Reduction to First-Order Systems) Every explicit ODE of order n can be rewritten as an equivalent first-order system by introducing the derivatives as new state variables. A general implicit higher-order equation can likewise be written as a first-order implicit system \bm{F}(\bm{Y},\bm{Y}',t)=0; it need not define an explicit ODE unless suitable solvability conditions hold.
Proof. To transform a higher-order differential equation into a system of first-order equations, we introduce auxiliary variables for each derivative of \bm{z}(t):
\begin{aligned} z_0(t) &= z(t), \\ z_1(t) &= z'(t), \\ & \vdots \\ z_{n-1}(t) & = z^{(n-1)}(t) \end{aligned}
This allows us to rewrite the original n-th order differential equation as a system of n first-order equations:
\begin{pmatrix} z'_0(t) - z_1(t) \\[0.5em] z'_1(t) - z_2(t) \\[0.5em] \vdots \\[0.5em] z'_{n-2}(t) - z_{n-1}(t) \\[0.5em] f\left(z_0(t), z_1(t), \dots, z_{n-1}(t), z'_{n-1}(t),t\right) \end{pmatrix} = \begin{pmatrix} 0 \\[0.5em] 0 \\[0.5em] \vdots \\[0.5em] 0 \\[0.5em] 0 \end{pmatrix}
In the case of an explicit equation, this system becomes:
\begin{pmatrix} z'_0(t) \\[0.5em] z'_1(t) \\[0.5em] \vdots \\[0.5em] z'_{n-2}(t) \\[0.5em] z'_{n-1}(t) \end{pmatrix} = \begin{pmatrix} z_1(t) \\[0.5em] z_2(t) \\[0.5em] \vdots \\[0.5em] z_{n-1}(t) \\[0.5em] f\left(z_0(t), z_1(t), \dots, z_{n-1}(t),t\right) \end{pmatrix}
Most often, ODEs come with additional information in the form of an initial condition, leading to what is known as an initial value problem (IVP), also referred to as a Cauchy problem. The initial condition specifies the value of the function z at a given point t_0 within the domain, helping to define a unique solution to the differential equation.
Definition 6.4 (Initial Value Problem (IVP)) Given an initial point
(t_0,\bm{z}_0) \in \mathbb{R} \times \mathbb{R}^d
let f(\bm{z}(t),t) be a function with values in \mathbb{R}^d, defined in a neighborhood
I \times U \subset \mathbb{R} \times \mathbb{R}^d
around the initial point. The initial value problem (IVP) is then the task of finding a function \bm{z}(t) such that:
\left\{ \begin{aligned} \bm{z}'(t) &= f(\bm{z}(t),t) \\[0.25em] \bm{z}(t_0) &= \bm{z}_0 \end{aligned} \right.
In the study of ordinary differential equations (ODEs), the concept of a local solution plays a fundamental role in understanding the behavior of dynamical systems. Given an initial value problem (IVP), a local solution refers to a function that satisfies the differential equation and initial condition within a limited region around the initial time.
Local solutions are particularly important because existence theorems, such as the Picard-Lindelöf Theorem 6.3, often guarantee solutions only within a small interval rather than over the entire domain. This is due to factors like nonlinearities in the system, singularities, or rapidly growing solutions that may prevent global existence.
Definition 6.5 (Local Solution) A local solution to the IVP is a continuously differentiable function \bm{z}(t) that satisfies \bm{z}(t_0) = \bm{z}_0. This solution exists within some neighborhood J of t_0, where both \bm{z}(t) and \bm{f}(\bm{z}(t),t) are well-defined, and the equation holds for all t \in J.
6.5 Well-Posedness, Existence, and Uniqueness
Definition of a Well-Posed Initial Value Problem
A mathematical problem is said to be well-posed if it satisfies the following conditions (Hadamard conditions):
- Existence: a solution exists.
- Uniqueness: the solution is unique.
- Continuous Dependence: the solution continuously depends on the initial data.
If any of these conditions fail, the problem is considered ill-posed, meaning small changes in the initial conditions can lead to large deviations in the solution.
Existence of Solutions
The following result provides a general existence theorem for first-order differential equations.
Theorem 6.1 (Peano’s Existence Theorem) Let f(\bm{z},t) be a continuous function defined on the closed set:
\bar{D} = \left\lbrace (t, \bm{z}) \in \mathbb{R} \times \mathbb{R}^d ~\big|~ |t - t_0| \leq \alpha, \|\bm{z} - \bm{z}_0\| \leq \beta \right\rbrace
where \alpha, \beta > 0. Then, there exists a continuously differentiable solution \bm{z}(t) \in C^1(I) on the interval I = [t_0 - T, t_0 + T], where:
T = \min \left(\alpha, \frac{\beta}{M} \right), \quad M = \max_{(t,\bm{z}) \in \bar{D}} \|\bm{f}(\bm{z},t)\|
This theorem guarantees existence but does not ensure uniqueness. If M=0, the solution is constant and one may simply take T=\alpha.
Continuation of solutions
Local existence does not by itself imply existence for all time. A precise continuation statement is the following.
Theorem 6.2 (Continuation theorem) Let D\subset\mathbb R\times\mathbb R^d be open and let \bm{f}:D\to\mathbb R^d be continuous and locally Lipschitz with respect to \bm{z}. Let \bm{z}:(\alpha,\beta)\to\mathbb R^d be the maximal solution of the IVP. If \beta<+\infty, then the graph (t,\bm{z}(t)) leaves every compact subset of D as t\uparrow\beta. Equivalently, if the graph remains in a compact subset K\Subset D, the solution can be extended beyond \beta.
Thus finite-time termination can occur because the solution becomes unbounded or because its graph approaches the boundary of the domain. Merely saying that \bm{f} is bounded at the points already reached is not, by itself, a complete continuation criterion.
Uniqueness of Solutions
To ensure uniqueness, we require stronger conditions such as Lipschitz continuity. We also introduce Grönwall’s Lemma, a crucial tool for proving uniqueness.
Lipschitz Condition
A function \bm{f}:D\to\mathbb R^d, with D=I\times\Omega\subset\mathbb R\times\mathbb R^d, is Lipschitz continuous with respect to the state variable, uniformly in t, if there exists L\ge0 such that
\|\bm{f}(\bm{x},t)-\bm{f}(\bm{z},t)\| \le L\|\bm{x}-\bm{z}\|, \qquad \forall t\in I,\quad \forall\bm{x},\bm{z}\in\Omega.
If such a constant exists on the whole domain, \bm{f} is globally Lipschitz in the state variable. If every point has a neighborhood on which such an estimate holds (equivalently, one has a suitable constant on each compact subset contained in the domain), \bm{f} is locally Lipschitz in the state variable.
Local Lipschitz continuity with respect to the state variable, together with continuity in t, is a standard sufficient condition for local uniqueness. It is sufficient, not necessary.
Grönwall’s Lemma
Lemma 6.2 (Grönwall Inequality) Let u:[t_0,T]\to[0,\infty) be continuous and suppose
u(t)\le A+\int_{t_0}^t b(s)u(s)\,\mathrm ds, \qquad A\ge0,
where b:[t_0,T]\to[0,\infty) is integrable. Then
\boxed{ u(t)\le A\exp\!\left(\int_{t_0}^t b(s)\,\mathrm ds\right) }.
Proof
Define
v(t)=A+\int_{t_0}^t b(s)u(s)\,\mathrm ds.
Then u(t)\le v(t) and v is absolutely continuous. For almost every t,
v'(t)=b(t)u(t)\le b(t)v(t).
Let
B(t)=\int_{t_0}^t b(s)\,\mathrm ds.
Multiplying the differential inequality by the integrating factor e^{-B(t)} gives, for almost every t,
\frac{\mathrm d}{\mathrm dt}\left(e^{-B(t)}v(t)\right) =e^{-B(t)}\bigl(v'(t)-b(t)v(t)\bigr)\le0.
Hence e^{-B(t)}v(t)\le v(t_0)=A, and therefore
v(t)\le A e^{B(t)}.
Since u(t)\le v(t), the claimed estimate follows. \square
A useful special case is b(s)=L, which gives
u(t)\le A e^{L(t-t_0)}.
The case A=0 is especially important: then the estimate forces u(t)=0 identically. This is the mechanism behind the uniqueness proof below.
A slightly more general form, useful for perturbation estimates, is
u(t)\le a(t)+\int_{t_0}^t b(s)u(s)\,\mathrm ds,
where a is non-negative and non-decreasing. The same argument yields
u(t)\le a(t)\exp\!\left(\int_{t_0}^t b(s)\,\mathrm ds\right).
Existence and Uniqueness
Picard–Lindelöf Theorem
The Picard-Lindelöf theorem (also called the Cauchy-Lipschitz theorem) strengthens Peano’s theorem by guaranteeing both existence and uniqueness of solutions.
Theorem 6.3 (Picard–Lindelöf) Let \bm{f}(\bm{z},t) be continuous on the cylinder:
D = \{ (t, \bm{z}) \in \mathbb{R} \times \mathbb{R}^d ~\big|~ |t - t_0| \leq a, \|\bm{z} - \bm{z}_0\| \leq b \}
Because D is compact and \bm{f} is continuous, it is automatically bounded; define
M=\max_{(t,\bm{z})\in D}\|\bm{f}(\bm{z},t)\|.
Assume in addition that \bm{f} satisfies a Lipschitz condition with respect to the state variable with constant L:
\|\bm{f}(\bm{x},t) - \bm{f}(\bm{z},t)\| \leq L \|\bm{x} - \bm{z}\|, \quad \forall (t,\bm{x}),(t,\bm{z}) \in D
Then, the initial value problem:
\left\{ \begin{aligned} \bm{z}'(t) &= \bm{f}(\bm{z}(t),t) \\[0.25em] \bm{z}(t_0) &= \bm{z}_0 \end{aligned} \right.
has a unique solution on the interval I = [t_0 - T, t_0 + T], where:
T = \min \left( a, \frac{b}{M} \right)
with the convention b/M=+\infty if M=0.
Proof by Picard Iteration
It is enough to prove the result on the forward interval
I_+=[t_0,t_0+T].
The proof on [t_0-T,t_0] is identical after reversing time, and uniqueness allows the two solutions to be joined. In what follows write I=I_+.
Start from the constant function
\bm{z}^{(0)}(t)=\bm{z}_0.
Define recursively the Picard iterates
\boxed{ \bm{z}^{(n+1)}(t) =\bm{z}_0+\int_{t_0}^t \bm{f}\bigl(s,\bm{z}^{(n)}(s)\bigr)\,\mathrm ds }.
We prove existence in four steps.
1. Every Picard iterate remains inside the cylinder. If \bm{z}^{(n)}(t) belongs to the state ball \|\bm{z}-\bm{z}_0\|\le b, then
\begin{aligned} \|\bm{z}^{(n+1)}(t)-\bm{z}_0\| &\le \int_{t_0}^t \|\bm{f}(\bm{z}^{(n)}(s),s)\|\,\mathrm ds \\ &\le M|t-t_0|\le MT\le b. \end{aligned}
Since \bm{z}^{(0)} is in the ball, induction shows that every iterate is well defined on all of I and remains in the cylinder D.
2. The sequence is uniformly Cauchy. The first difference satisfies
\|\bm{z}^{(1)}(t)-\bm{z}^{(0)}(t)\|\le M|t-t_0|.
Using the Lipschitz condition and induction, one obtains
\boxed{ \|\bm{z}^{(n+1)}(t)-\bm{z}^{(n)}(t)\| \le M L^n\frac{|t-t_0|^{n+1}}{(n+1)!} }.
Indeed, assuming the estimate at level n-1,
\begin{aligned} \|\bm{z}^{(n+1)}(t)-\bm{z}^{(n)}(t)\| &\le L\int_{t_0}^t \|\bm{z}^{(n)}(s)-\bm{z}^{(n-1)}(s)\|\,\mathrm ds\\ &\le ML^n\frac{|t-t_0|^{n+1}}{(n+1)!}. \end{aligned}
Therefore, uniformly for t\in I,
\|\bm{z}^{(n+1)}(t)-\bm{z}^{(n)}(t)\| \le ML^n\frac{T^{n+1}}{(n+1)!}.
The scalar series
\sum_{n=0}^{\infty}ML^n\frac{T^{n+1}}{(n+1)!}
converges. By the Weierstrass test, \bm{z}^{(n)} converges uniformly on I to a continuous function \bm{z}. Notice that this factorial estimate proves convergence without requiring LT<1.
3. The limit satisfies the integral equation. Because \bm{f} is Lipschitz in the state variable,
\|\bm{f}(\bm{z}^{(n)}(t),t)-\bm{f}(\bm{z}(t),t)\| \le L\|\bm{z}^{(n)}(t)-\bm{z}(t)\|,
so the integrands also converge uniformly. Passing to the limit in the Picard equation gives
\bm{z}(t)=\bm{z}_0+\int_{t_0}^t\bm{f}(\bm{z}(s),s)\,\mathrm ds.
Since the integrand is continuous, the fundamental theorem of calculus implies
\bm{z}'(t)=\bm{f}(\bm{z}(t),t), \qquad \bm{z}(t_0)=\bm{z}_0.
Thus a solution exists.
4. The solution is unique. Let \bm{y} and \bm{z} be two solutions with the same initial value. Then
\|\bm{y}(t)-\bm{z}(t)\| \le L\int_{t_0}^t\|\bm{y}(s)-\bm{z}(s)\|\,\mathrm ds
for t\ge t_0; the backward-time argument is identical after reversing the integration limits. Grönwall’s lemma with A=0 yields
\bm{y}(t)=\bm{z}(t)
throughout I. Hence the solution is unique. \square
Remark. A shorter proof can be obtained from Banach’s fixed-point theorem on a sufficiently short interval satisfying LT<1. The factorial estimate above is slightly stronger pedagogically because it shows directly why the Picard sequence converges on the whole interval allowed by the cylinder bound MT\le b.
Why the Lipschitz Condition Gives Uniqueness
Suppose \bm{y} and \bm{z} are two solutions with the same initial value. Their integral equations give
\|\bm{y}(t)-\bm{z}(t)\| \le \int_{t_0}^t \|\bm{f}(\bm{y}(s),s)-\bm{f}(\bm{z}(s),s)\|\,\mathrm ds \le L\int_{t_0}^t\|\bm{y}(s)-\bm{z}(s)\|\,\mathrm ds.
Grönwall’s inequality with A=0 yields \|\bm{y}(t)-\bm{z}(t)\|=0. Hence \bm{y}(t)=\bm{z}(t) throughout their common interval of existence.
Continuous Dependence on Initial Data
If \bm{y}(t_0)=\bm{y}_0 and \bm{z}(t_0)=\bm{z}_0, the same argument gives
\boxed{\|\bm{y}(t)-\bm{z}(t)\|\le e^{L|t-t_0|}\|\bm{y}_0-\bm{z}_0\|.}
Thus the same hypothesis that gives uniqueness also yields a quantitative form of continuous dependence and therefore local well-posedness.
Counterexample: Existence Without Uniqueness
Consider the ordinary differential equation (ODE):
y' = \sqrt{|y|}
with the initial condition:
y(0) = 0.
Existence of the Solution
Peano’s Theorem guarantees that if a function f(y,t) is continuous, then there exists at least one solution within some interval around the initial point. In this case, the function f(y) = \sqrt{|y|} is continuous for all values of y, so Peano’s theorem tells us that there exists at least one solution for the given ODE, at least in a small interval around t = 0.
Thus, we can assert that there exists a function y(t) that satisfies the differential equation and the initial condition y(0) = 0.
Failure of Uniqueness
Picard-Lindelöf Theorem 6.3 states that, in addition to existence, a solution is also unique if the function f(y,t) is Lipschitz continuous with respect to y in an interval around the initial condition y_0. However, in our case, the function f(y) = \sqrt{|y|} is not Lipschitz continuous at y = 0.
To verify this, let’s compute the derivative of f(y) = \sqrt{|y|}:
f'(y) = \left\{ \begin{aligned} \frac{1}{2\sqrt{y}} & y > 0 \\[0.5em] -\frac{1}{2\sqrt{-y}} & y < 0 \end{aligned} \right. =\frac{\operatorname{sign}(y)}{2\sqrt{|y|}},\qquad y\ne0
Notice that this derivative becomes infinite as y \to 0, so the function is not Lipschitz continuous at y = 0. A bounded derivative on a neighborhood would imply Lipschitz continuity by the mean-value theorem. Here one can prove failure directly: for y>0, |f(y)-f(0)|/|y|=1/\sqrt y\to\infty.
Since f(y) = \sqrt{|y|} does not satisfy the Lipschitz condition at y = 0, Picard-Lindelöf Theorem 6.3 does not guarantee the uniqueness of the solution. This means there may be more than one solution that satisfies the same initial condition y(0) = 0.
Multiple Solutions
Even though a solution exists, it is not unique. In fact, there are many solutions that satisfy the ODE and the initial condition y(0) = 0. Here are a few examples:
Trivial (Zero) Solution
One solution is the zero solution, where y(x) = 0 for all x. This is a solution that satisfies both the ODE and the initial condition y(0) = 0, and it holds for every value of x.
y(x) = 0 \quad \text{for all} \quad x.
Explicit (Non-Zero) Solution
Another solution can be found by solving the ODE by separating the variables. We start by writing the ODE as:
\frac{\mathrm{d}y}{\sqrt{|y|}} = \mathrm{d}x.
Integrating both sides:
2\sqrt{|y|} = x + C.
Setting the initial condition y(0) = 0, we get C = 0. Therefore, the solution becomes:
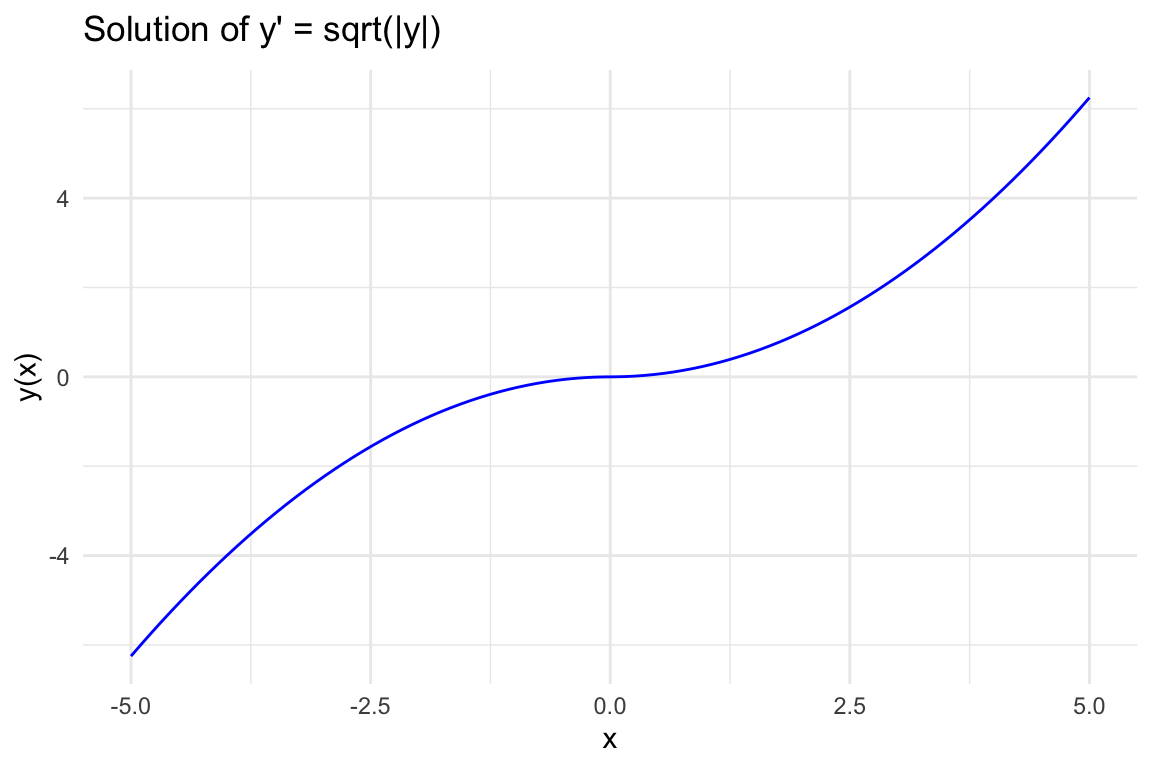
y(x) = \frac{x^2}{4}, \quad \text{for} \quad x \geq 0.
This is an explicit solution for x \geq 0 and satisfies the ODE and the initial condition.
For x < 0, the solution must be:
y(x) = -\frac{x^2}{4}, \quad \text{for} \quad x < 0,
to match the sign of the right-hand side. Thus, the complete solution is:
y(x) = \frac{x^2}{4} \begin{cases} 1 & x \geq 0, \\ -1 & x < 0. \end{cases}
This can also be written more compactly as:
y(x) = \frac{x|x|}{4}.
The derivative of this function is:
y'(x) = \frac{x}{2} \begin{cases} 1 & x \geq 0, \\ -1 & x < 0. \end{cases}
Which simplifies to:
y'(x) = \frac{|x|}{2}.
Notice that:
\sqrt{|y(x)|} = \sqrt{\left|\frac{x|x|}{4}\right|} = \sqrt{\frac{|x|^2}{4}} = \frac{|x|}{2} = y'(x).
Thus, the function y(x) = \frac{x|x|}{4} satisfies the ODE, and it is indeed a valid solution.
A Whole Family of Solutions
The non-uniqueness is stronger than the two examples above. For arbitrary numbers a\le0\le b,
y_{a,b}(t)= \begin{cases} -\frac{(t-a)^2}{4}, & t<a,\\[0.4em] 0, & a\le t\le b,\\[0.4em] \frac{(t-b)^2}{4}, & t>b \end{cases}
is continuously differentiable, satisfies y_{a,b}(0)=0, and obeys y'_{a,b}=\sqrt{|y_{a,b}|}. The solution may therefore remain at the equilibrium for an arbitrary waiting time before leaving it. This explicitly proves non-uniqueness; failure of the Lipschitz hypothesis alone would only tell us that Picard–Lindelöf cannot be used.
Conclusion
The ODE y' = \sqrt{|y|} with the initial condition y(0) = 0 has multiple solutions. In addition to the trivial solution y(x) = 0, we also have non-zero solutions of the form:
y(x) = \frac{x|x|}{4}.
These multiple solutions are possible due to the lack of uniqueness in this case, as the function f(y) = \sqrt{|y|} is not Lipschitz continuous at y = 0.
Summary
- An initial value problem is well posed when a solution exists, is unique, and depends continuously on the data; the three requirements are independent and each can fail separately.
- Peano’s theorem gives existence from continuity alone, but not uniqueness: y'=\sqrt{|y|} with y(0)=0 has infinitely many solutions.
- A Lipschitz condition in y restores uniqueness. Picard–Lindelöf turns the IVP into a fixed-point problem for the Volterra integral operator and gives local existence and uniqueness by contraction.
- Grönwall’s lemma is the workhorse: it converts an integral inequality into an exponential bound, and it yields both uniqueness and continuous dependence on the initial data, with the amplification factor e^{L(t-t_0)} that will reappear in every convergence estimate of the numerical chapters.
- A local solution extends until it leaves every compact subset of the domain; a global Lipschitz condition rules out blow-up in finite time.
- For autonomous systems, linearization at an equilibrium reduces the local question to the eigenvalues of the Jacobian — the same eigenvalues that govern stiffness and the choice of step size later on.